I’m building automated trading bots for Polymarket. The work sits somewhere between market research and systems engineering: processing live data, deciding what to quote, and dealing with what actually happens after an order goes out.
- My role
- Independent developer and researcher
- Stack
- Python, Rust, WebSockets, REST APIs
- Focus
- Market making and event-driven execution
- Status
- Ongoing personal project
What I’m building
One part of the project is market making: placing quotes on both sides of a market and studying when those quotes get filled. Another is event-driven execution, looking at price dislocations around changes in the underlying market or event.
Both depend on the same basic problem. A strategy needs a useful picture of the market before it can make a useful decision. That means handling order-book updates, market data, and external price feeds as events arrive.
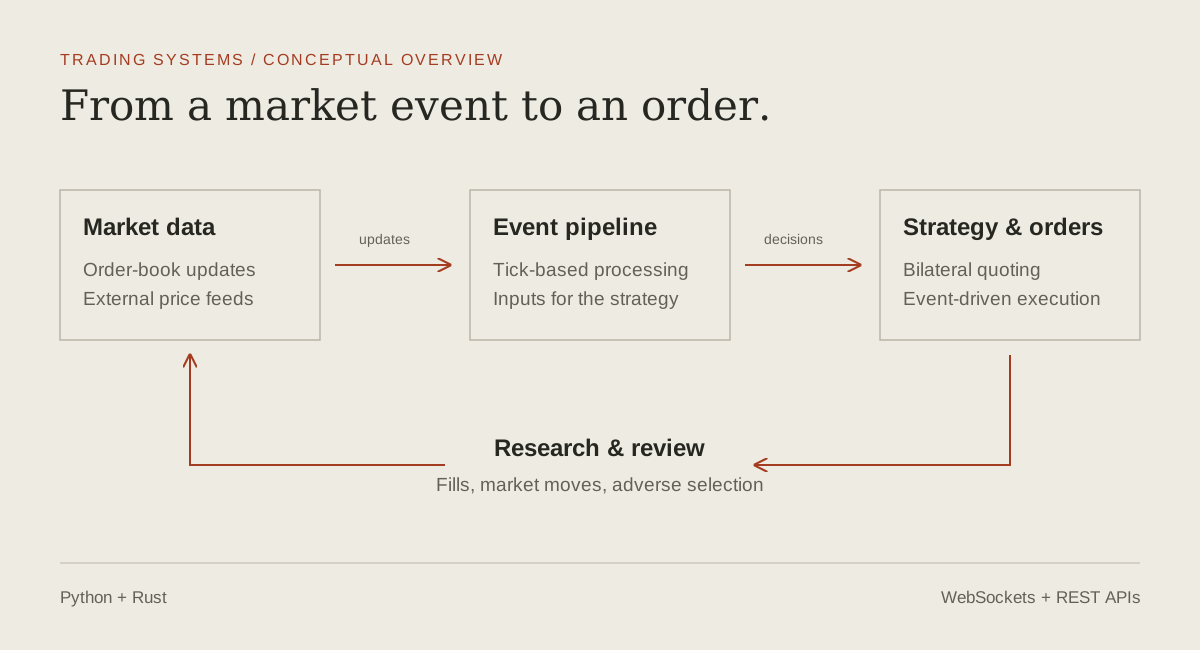
From data to an order
- Receive market events. WebSocket feeds provide order-book and price updates; REST APIs cover request/response interactions with the market.
- Process the updates. Tick-based pipelines turn incoming events into inputs for the strategy.
- Make an execution decision. The bot evaluates quotes or an event-driven opportunity and interacts with the order API.
- Study the result. Execution and market data feed back into the research, including analysis of adverse selection.
Why the fills matter
For a market-making strategy, getting filled is only part of the story. A quote can look attractive when it is placed, then get hit just as the market moves against it. That is why adverse selection is a central part of this work.
I’m interested in the connection between the strategy and its execution: the data the bot saw, the decision it made, and what the market did afterwards. It gives me a much more useful way to examine a trading system than looking at an isolated signal.
What this project brings together
This is where I use Python and Rust alongside streaming APIs and market data. It combines the research side of my Data Science background with the operational questions I deal with at work: what state is the system in, what changed, and how do I explain its behaviour?
The project is ongoing. This page is an engineering overview; it doesn’t publish private strategy parameters, account details, or trading performance claims.
Related work
Before this, I built MT4/MT5 FX trading bots. I’ve also written about reconstructing a midnight scalping strategy from old trade logs and researching a regime-aware DCA strategy. Both write-ups are in the writing archive.